ECB Monetary Policy and the German Economy, 1999–2023
Final report for the course Financial Institutions and Markets (Dr. Wenjun Xue), SILC Business School, Shanghai University, January 2026.
Abstract
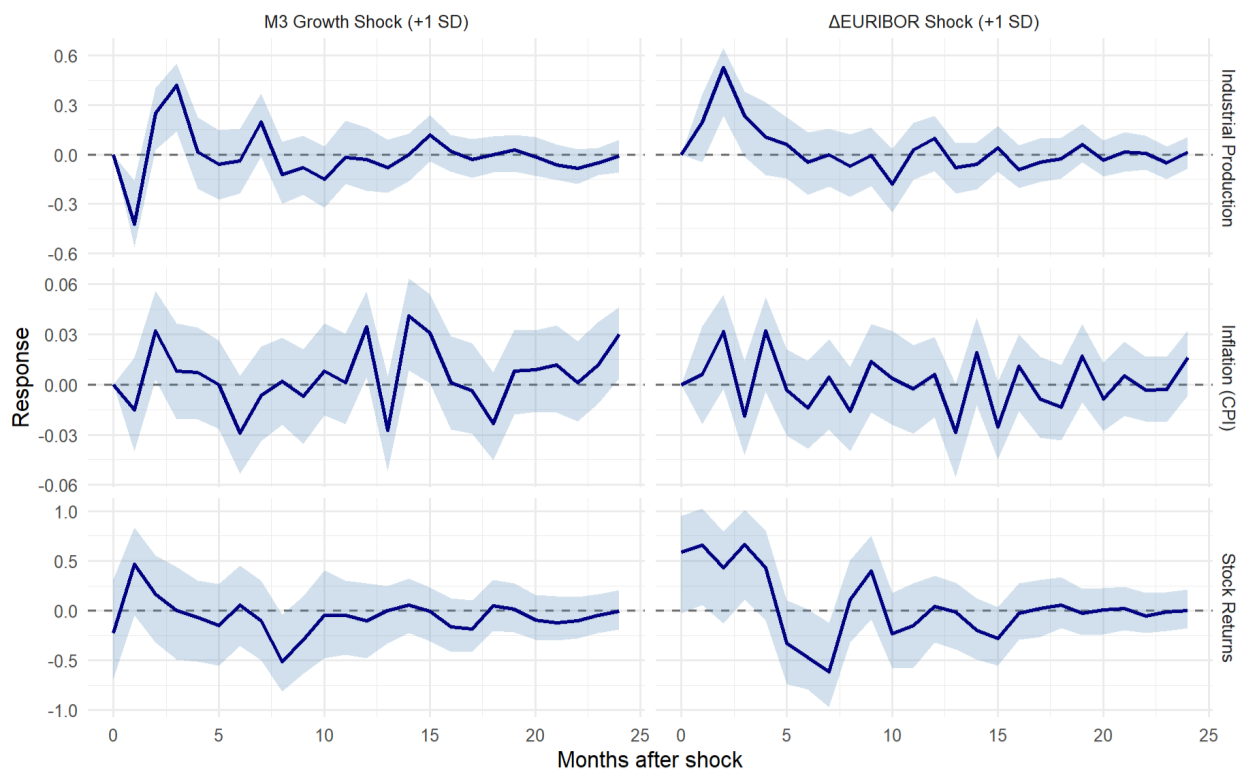
This report examines how conventional ECB monetary policy instruments transmit to the German economy over the 1999 to 2023 period, using a baseline OLS specification, local projections, and a Cholesky-identified VAR. Three findings emerge consistently. Shocks to the broad monetary aggregate M3 generate no systematic response in German prices, real activity, or equity returns. A positive EURIBOR shock depresses German equity returns sharply at medium horizons, in line with the asset price channel. The effect on inflation is weakly visible in the local projections but not robust to the structural setting, and the response of industrial production exhibits a persistent output puzzle. Conventional ECB instruments thus appear to transmit most reliably to financial markets, less reliably to inflation, and not measurably through the broad aggregate.